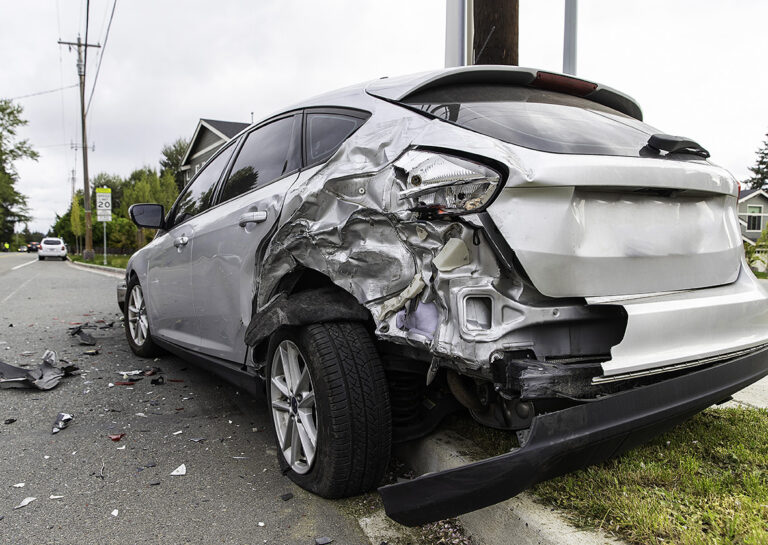
What Is UM/UIM Coverage and Why Does It Matter After a Texas Car Accident?
You buy auto insurance hoping you never have to use it.
But after a serious car accident, one question can quickly become important:
“What happens if the driver who caused the crash doesn’t have insurance, or doesn’t have enough?”
This is where uninsured and underinsured motorist coverage, commonly called UM/UIM coverage, may come into play.
For many Texas drivers, UM/UIM coverage can provide an additional source of financial protection after an accident involving a driver with little or no insurance. In Texas, insurers generally must offer UM/UIM coverage unless the named insured rejects it in writing.
Understanding what this coverage does before an accident happens can make a major difference.
What Is UM/UIM Coverage?
UM/UIM stands for:
- UM: Uninsured Motorist Coverage
- UIM: Underinsured Motorist Coverage
Although they are often grouped together, they can apply in different situations.
Uninsured Motorist Coverage
Uninsured motorist coverage may apply when the driver responsible for an accident does not have liability insurance available to cover your damages.
It may also be relevant in certain hit-and-run situations, depending on the facts and the requirements of the policy and Texas law.
Underinsured Motorist Coverage
Underinsured motorist coverage may apply when the at-fault driver has insurance, but the available liability coverage is not enough to compensate for the damages you are legally entitled to recover, subject to the terms and limits of the applicable policies.
In other words, the driver who caused the accident may technically be insured, but their policy limits may still fall short after a serious injury.
Why Is UM/UIM Coverage Important in Texas?
Texas law requires drivers to carry liability insurance, but not every driver follows the law.
According to the Texas Department of Insurance, more than 2.4 million state-registered vehicles were not matched to an insurance policy in a 2025 report, approximately 12% of registered vehicles.
Even when an at-fault driver has insurance, the minimum or available coverage may not be enough to address serious injuries, extensive medical treatment, lost income, and other damages.
A crash involving a serious injury can quickly become expensive.
You may be facing:
-
Emergency medical care
-
Surgery or hospitalization
-
Physical therapy and rehabilitation
-
Lost income
-
Vehicle repairs or replacement
-
Ongoing medical treatment
-
Pain and suffering
What Can UM/UIM Coverage Help Pay For?
The specific coverage available depends on the policy and the circumstances of the accident.
According to the Texas Department of Insurance, UM/UIM coverage may help with certain losses, including:
- Medical expenses
- Vehicle repairs
- Property damaged in the vehicle
- A rental vehicle, when applicable
- Diminished value
- Pain and suffering
Coverage may also extend to passengers in certain circumstances. The exact benefits available will depend on the policy language, coverage limits, and facts of the claim.
UM/UIM Coverage Is Not the Same as PIP
UM/UIM and Personal Injury Protection, or PIP, are two different types of coverage.
PIP may provide benefits for certain medical expenses and lost income resulting from an accident, regardless of who caused the crash, subject to the terms and limits of the policy.
UM/UIM coverage, on the other hand, generally involves situations where another driver is legally responsible for your damages but has no insurance or insufficient insurance available.
Depending on the circumstances and your insurance coverage, more than one type of coverage may need to be reviewed after an accident.
What Happens If the Other Driver Has the Minimum Insurance?
Having insurance does not necessarily mean there will be enough coverage available after a serious crash.
For example, imagine you are seriously injured by another driver. Their insurance policy may provide coverage, but your medical expenses and other losses may exceed the amount available under that policy.
In some situations, UIM coverage may become relevant if the available liability coverage is less than the applicable UIM coverage and the injured person’s legally recoverable damages exceed the available liability coverage.
However, every case is different. The amount available can depend on multiple factors, including:
- The insurance policies involved
- The available policy limits
- The amount of damages
- Whether there are multiple injured parties
- Liability for the accident
- The specific terms and conditions of the policy
Maybe you had back pain before the crash. Maybe you previously injured your shoulder. Maybe you already had arthritis.
That doesn’t automatically mean the accident didn’t cause or worsen your injuries.
An accident can aggravate a condition that existed before the crash. Medical evidence is often important in determining what changed after the collision.
Don’t assume you don’t have a claim simply because you weren’t perfectly healthy before the accident.
Do You Automatically Have UM/UIM Coverage in Texas?
Texas insurers generally must provide UM/UIM coverage with an automobile liability policy unless a named insured rejects the coverage in writing.
However, you should never assume you have a certain type or amount of coverage.
Review your policy or speak with your insurance agent to understand:
- Whether you have UM/UIM coverage
- Your bodily injury coverage limits
- Your property damage coverage limits
- Whether any exclusions or policy conditions may apply
It is much easier to understand your insurance coverage before you need to use it.
What Should You Do After an Accident With an Uninsured or Underinsured Driver?
If you are injured in an accident, taking the right steps can help protect your health and preserve important information.
1. Seek Medical Attention
Your health should come first. Some injuries may not be immediately apparent after a crash.
2. Call Law Enforcement When Appropriate
A police report may contain important information about the accident, including the drivers involved and available insurance information.
3. Document the Accident
If you can safely do so, take photographs of:
- The vehicles
- The accident scene
- Visible injuries
- Road conditions
- Property damage
Also keep copies of medical records, bills, repair estimates, and other documents related to the crash.
4. Review All Available Insurance Coverage
The at-fault driver’s policy may not be the only policy that matters.
Depending on the circumstances, your own auto policy may include UM/UIM coverage or other benefits that could apply.
5. Be Careful Before Agreeing to a Settlement
A settlement involving the at-fault driver’s insurance company could affect other aspects of your claim depending on the policies involved and the circumstances.
Before signing a release or finalizing a settlement, it can be important to understand what rights or insurance coverage may still be available.
How Can Carabin Law Help?
After a serious accident, figuring out insurance coverage can be confusing, especially when the driver who caused the crash has little or no insurance.
At Carabin Law, we understand that investigating an accident involves more than determining who was at fault. It may also involve identifying available insurance coverage and understanding how different policies could apply to your situation.
Our team can review the circumstances surrounding your accident, investigate the evidence, and help you understand the options available to you.
Every Case Matters. Every Client Counts.
If you or someone you love was injured in a Texas car accident, contact Carabin Law to discuss your case.
This blog is for general informational purposes only and is not intended to provide legal advice. Every case is different, and the information in this article does not create an attorney-client relationship.